💵
Value My Car → We Buy Cars — Even If You Don’t Buy From Us.
Get a real offer on your vehicle in minutes. No obligation, no pressure.
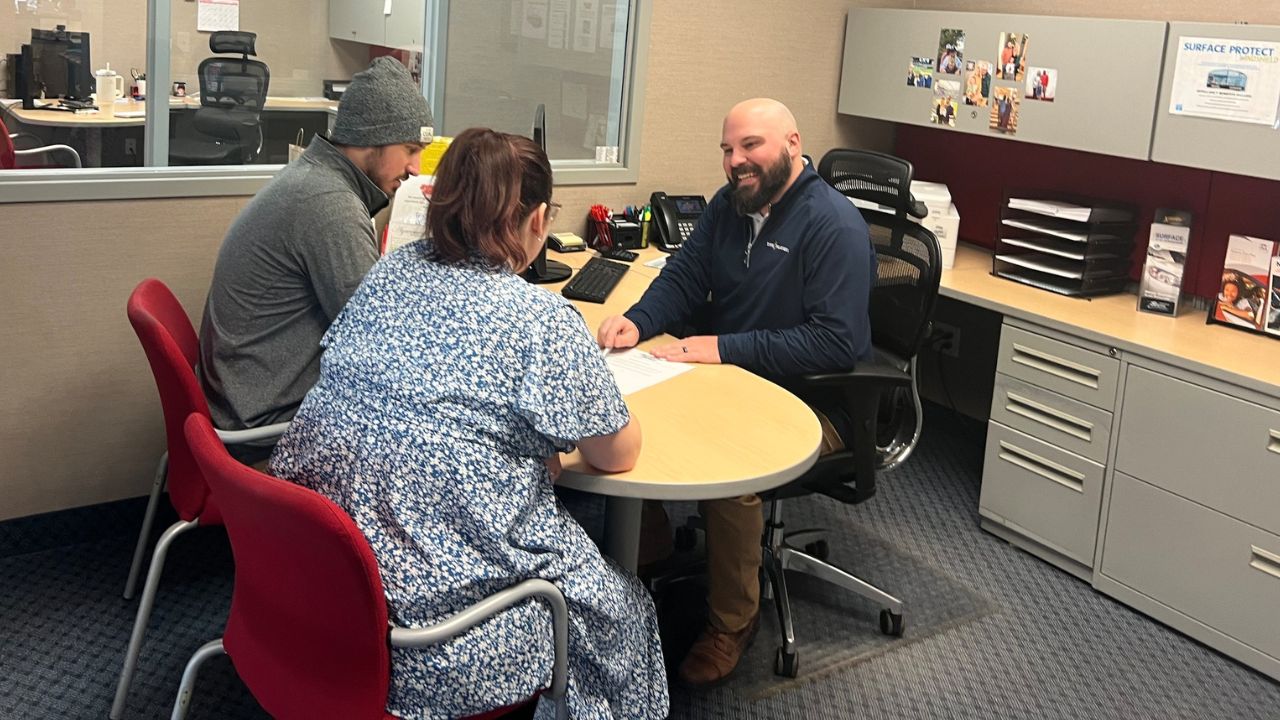
I have sat across the desk from a lot of nervous people. Not nervous about the vehicle — they usually know exactly which one they want by the time they get to me. Nervous about the financing. Specifically, nervous that someone is about to tell them no.
If you are buying your first vehicle and you have never had a car loan, you have probably already heard some version of “you need credit to get credit.” That is only half true, and the half that is false is the half that matters. Here is what actually determines whether a first-time buyer gets financed in Minnesota, in plain language, from someone who does this every week.
The quick answer
Yes, you can buy a car with no credit history. Lenders look at more than a credit score — steady income, time on the job, a clean record, and money down all carry weight. Ford Credit also runs a First-Time Buyer Program specifically for people with no prior auto loan, which is designed to get qualified buyers a better rate than a no-history applicant would normally see.
What is covered
Can you actually buy a car with no credit history?
What credit score do you need to buy your first car?
How much should you put down on your first vehicle?
Do you need a co-signer for your first car loan?
What is the Ford Credit First-Time Buyer Program?
Start here
Can you actually buy a car with no credit history?
Yes. No credit history is not the same thing as bad credit, and lenders do not treat them the same way. Bad credit means there is a record and the record is rough. No credit means there is no record yet. Those are very different problems, and the second one is much easier to solve.
What happens without an auto loan on your file is that a lender has less to go on, so they price the risk higher. That is where a lot of first-time buyers get quoted a rough rate and walk away thinking they were rejected. Usually they were not rejected. They were quoted a no-history rate.
That is exactly the gap the Ford Credit First-Time Buyer Program is built to close. It is designed for people with no prior auto tradelines, so the absence of a car loan on your record is the qualifier rather than the obstacle.
The question I get most
What credit score do you need to buy your first car?
There is a minimum score for this program, and it is lower than most first-time buyers assume. But I am going to give you a more useful answer than a number, because the number by itself misleads people more often than it helps.
Here is the part almost nobody knows: the score you see on a free credit app is usually not the score an auto lender pulls. Lenders commonly use auto-specific scoring models that weigh your history differently than the general-purpose score on your phone. It is normal for those two numbers to be meaningfully apart, in either direction. I have had people come in convinced they were in trouble and score better than they expected, and I have had the reverse.
Score is also one input among several. Time on the job, whether the income is steady and documentable, whether there is a repossession or bankruptcy in the file, and how much you are putting down all move the outcome. A thin file with a solid job and money down can beat a slightly higher score with no work history behind it.
The practical move: stop guessing and find out. Getting pre-qualified uses a soft credit inquiry, which does not affect your score and is not visible to other lenders. It costs you nothing and takes a few minutes. Or call me and we will look at it together.
Money up front
How much should you put down on your first vehicle?
There is a required minimum for the First-Time Buyer Program, and it is low by design — that is one of the things the program exists to fix. Call us and we will tell you exactly what it is for your situation.
But the more honest answer is that the minimum and the smart amount are two different numbers. Every dollar you put down does three things at once: it lowers what you finance, it lowers your payment, and it makes the deal look better to the lender, which can help on the rate. Money down is the one lever a first-time buyer fully controls.
A couple of things people do not always realize count toward it:
A trade-in counts
If you have a vehicle now — even an old one — its value can go straight into the deal. Get a number on it before you assume it is worthless.
Rebates are separate
Manufacturer rebates reduce the price, but the program requires your own cash down on top of them. Rebates and trade equity do not substitute for it.
One more thing worth planning for in Minnesota: sales tax, title, registration, and plates are real money on top of the vehicle. Budget for them so they do not surprise you on delivery day.
The family question
Do you need a co-signer for your first car loan?
A lot of first-time buyers qualify on their own through this program — that is much of the point of it. But I am not going to tell you a co-signer never comes up, because sometimes it does. Depending on your credit history and how the underwriting comes back, a co-signer or a larger down payment can be what makes the deal work.
If a parent or family member is considering it, they should understand what they are signing. A co-signer is not a character reference. They are equally responsible for the loan, it appears on their credit, and if payments are missed it affects them the same as it affects you.
My advice: apply on your own first and see where you actually land. Then you know whether a co-signer is genuinely needed instead of bringing one along out of nervousness.
The program itself
What is the Ford Credit First-Time Buyer Program?
It is a joint program between Ford Credit and Ford Motor Company aimed squarely at buyers financing their first vehicle. Qualified applicants may be eligible for a lower APR than a no-history applicant would typically be quoted, plus bonus cash on eligible new Fords. It allows financing up to $50,000, and it covers both new Fords and eligible Ford Blue Advantage certified pre-owned vehicles from the current model year back through five model years old.
Ten new models qualify: Bronco, Bronco Sport, Escape, Explorer, F-150, F-150 Lightning, Maverick, Mustang, Mustang Mach-E, and Ranger. Around here, the Maverick and Escape are the two that come up most with first-time buyers, and the Ranger if there is a boat or a trailer in the picture.
There is a fuller breakdown of eligibility and how the process works on our First-Time Buyer Program page.
New or used
Should your first vehicle be new or certified pre-owned?
Both work under this program, and I genuinely do not push people one direction. It comes down to what you want the payment to buy.
New gets you full factory warranty, the newest safety and driver-assist tech, and nobody else's history. For a first vehicle you plan to keep a long time, that predictability has real value — and the bonus cash applies to new only.
Ford Blue Advantage certified vehicles are inspected, come with warranty coverage and a vehicle history report, and let the same payment reach a nicer trim or a bigger vehicle. If you want four-wheel drive and a real winter vehicle rather than the base version of something, certified is often how you get there.
One caution either way: do not stretch to the absolute top of what you are approved for. Approved and comfortable are different numbers. Insurance on a first vehicle is often higher than people expect, and fuel, tires, and maintenance are all still coming.
Come prepared
What should you bring to the dealership?
Showing up with the right paperwork is the difference between finishing in one visit and coming back twice. Bring:
A valid driver’s license
Proof of insurance
Recent pay stubs as proof of income
Trade-in title and lender info, if you have a trade
Depending on how your credit comes back, Ford Credit may ask for something additional such as proof of residence. If that happens I will tell you up front rather than letting you find out at the end.
Key takeaways
More questions
First-time buyer questions from around Hutchinson
You need to be 18 to sign a binding contract in Minnesota, which means 18 is the practical minimum to finance a vehicle in your own name. Buyers under 18 would need a parent or guardian as the buyer on the contract. Age itself is not what determines approval — income, employment, and credit history are.
Yes, if you pay it on time. An auto loan is an installment account, and consistent on-time payments build exactly the kind of history that thin credit files are missing. That is a real long-term benefit of financing a first vehicle rather than paying cash for something older. Missed payments do the reverse, so only take on a payment you are confident you can cover every month.
Possibly. What lenders want is income they can verify and a work history that shows stability. Part-time and seasonal income can count, but it usually needs documentation and it may affect how much you qualify for. Bring your pay stubs and let us look at the actual numbers rather than ruling yourself out ahead of time.
It is always worth comparing, and we are not offended if you do. What a bank or credit union usually cannot offer is a manufacturer program built specifically for first-time buyers, or manufacturer bonus cash tied to financing. Bring us whatever offer you have and we will tell you honestly how it compares.
If you have picked a vehicle and brought your paperwork, most first-time buyers are done in a couple of hours. Pre-qualifying online beforehand shortens it further because we already know roughly where you stand when you walk in. What takes longest is going back and forth on missing documents, which is why the list above matters.
If you take one thing from this: the worst outcome is not getting told no. The worst outcome is never asking, driving something unreliable through a Minnesota winter, and never starting the credit history that makes the next vehicle easier.
Come talk to me. Bring your questions, bring your pay stubs, and bring somebody with you if that makes it easier. There is no cost to finding out where you stand, and I will give you a straight answer either way.
About the Author
I’m Nick Betker, Finance Manager at Jay Malone Motors in Hutchinson, MN. I sit down with first-time buyers just about every week — people buying with no credit history, people whose parents came in with them, people who have been saving for a year and are nervous about the whole thing. My job is to explain what you are signing before you sign it and to be honest with you about what makes sense for your budget. If you have a question about financing your first vehicle, call me directly at (320) 587-4748.
This article is general information, not financial advice, and is current as of August 15, 2026. Eligibility does not guarantee credit approval. Financing is subject to Ford Credit approval and standard underwriting guidelines. Not all buyers will qualify. First-Time Buyer Bonus Cash requires Ford Credit financing and applies to eligible new Ford vehicles. Program terms, vehicle eligibility, incentives, and availability are subject to change without notice, and manufacturer rebates are updated periodically. Additional down payment, proof of income, or proof of residence may be required based on credit history and underwriting guidelines. Not compatible with 90-day deferred payment programs. One vehicle per customer. The Ford Credit First-Time Buyer Program is scheduled to run through December 31, 2026. See Jay Malone Ford for complete program details and current offers.